


Market Review June 2026
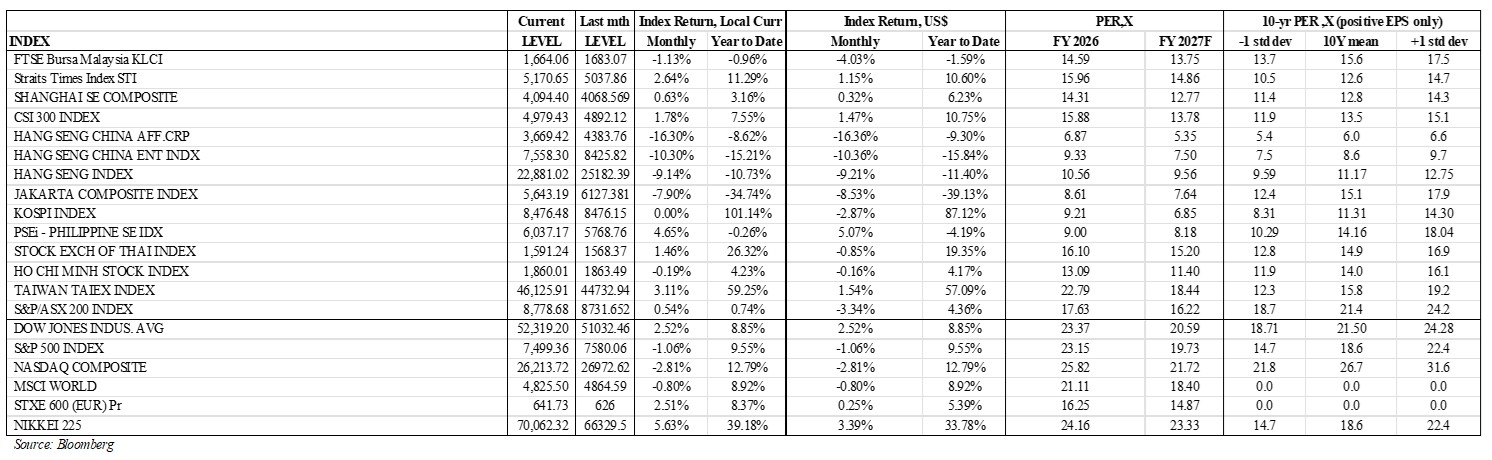
Despite positive demand and supply dynamic in the semiconductor industry on the back of strong AI capex , risk assets across major markets corrected during the month. North Asia markets, in particular Korea and Taiwan markets, softened as semiconductor stocks saw profit taking. Key AI beneficiaries, including TSMC, SK Hynix, Samsung Electronics, and major AI supply chain names, saw broad-based selling despite fundamentals remaining largely intact. The World Index declined 0.80% in June, while the MSCI Far East Ex. Japan index retraced 1.92%. Within the Asia region, ASEAN equities declined by 1.01%. The best performing indices were Philippines (+4.65%) and Taiwan (+3.11%) markets. Regional currencies mostly weakened against the USD. The best performing currencies were Philippines Peso (+0.43%) and Indian Rupee (+0.36%), while the weaker ones were Malaysia Ringgit (-2.93%) and Korean Won (-2.86%).
U.S. equity indices delivered mixed performance during the month as investor sentiment remained cautious amid ongoing geopolitical uncertainty, particularly surrounding the fragile ceasefire between the United States and Iran. The uncertain outlook for energy prices and inflation, coupled with heightened market volatility, continued to weigh on risk appetite. Much attention had been focused on the IPO of SpaceX which raised USD75 billion from the market and pricing the company at a market capitalization of USD1.75 trillion. For the month, Dow Jones Industrial Average (DJIA), S&P 500 Index and Nasdaq Composite gained 2.52%, -1.06% and -2.81% respectively. U.S. equity markets declined as investor sentiment weakened following a broad-based sell-off in semiconductor stocks. The pullback of the tech heavy indices was largely driven by profit-taking on growing concerns over whether elevated AI-related capital expenditure can continue to deliver sufficient earnings growth to justify current valuations. At the same time, expectations that interest rates may remain higher for longer weigh on high-growth technology stocks. A hawkish tone from Kevin Warsh following his first meeting as Fed Chairman came as a surprise to the market. Despite the recent correction, the market weakness appears to reflect a valuation reset within the technology sector rather than a deterioration in underlying economic fundamentals.
The STOXX Europe 600 Index gained 2.51% over the month, as investor sentiment remained cautious amid a weaker macroeconomic backdrop. The Eurozone economy lost momentum in 2Q26, with geopolitical tensions in the Middle East, uncertainty surrounding the fragile ceasefire, and softer external demand weighing on business confidence. As a result, companies adopted a more cautious stance towards capital expenditure and hiring. Nevertheless, domestic consumption remained the key driver of growth, supported by resilient household spending and government investment programs. However, tighter financial conditions and subdued export demand continued to constrain broader economic expansion. Meanwhile, Eurozone inflation continued to moderate in June 2026, with headline inflation easing to 2.8% YoY from 3.2% in the previous month, coming in below market expectations of 3.0%. Core inflation, which excludes volatile food and energy prices, also softened to 2.4% YoY from 2.6%, undershooting the consensus forecast of 2.5%. The latest data suggest underlying price pressures are gradually easing, supporting expectations that inflation is moving closer to the European Central Bank’s target. The ECB’s Lagarde described the risks to Eurozone inflation and economic growth as “broadly balanced”.
Hang Seng Index and Hang Seng China Enterprises Index declined 9.14% and 10.30% respectively, extending the respective 2.30% and 2.95% losses registered in May. China’s economy entered 2026 on a relatively firm footing, with real GDP expanding 5.0% in 1Q26, up from 4.5% in 4Q25. Nominal GDP growth also accelerated to 4.9%, its strongest pace in nearly three years, reflecting a gradual easing in deflationary pressures. However, economic momentum moderated in 2Q26, as softer external demand and rising input costs stemming from geopolitical tensions weighed on manufacturing activity. While the services sector continued to recover, the improvement remained insufficient to offset subdued consumer spending and the prolonged weakness in the property sector and rising unemployment rate. Moreover, financing activity continued to lose momentum, with both total social financing and new RMB loans falling short of market expectations, highlighting subdued borrowing demand from households and corporates despite ongoing policy support.
South Korea’s KOSPI Index edged down 2.87% in US term (0.00% in local term) following its strong 92.64% rally in the year to May. The market remained under pressure as investors rotated out of high-flying AI and semiconductor stocks, mirroring the broader correction seen across global technology markets. Profit taking in index-heavyweight chipmakers, including Samsung Electronics and SK Hynix, , weighed on the index. Investor sentiment was also tempered by valuation concerns, uncertainty over the sustainability of AI-related capital expenditure, and expectations that global interest rates may remain higher for longer. Nonetheless, South Korea’s trade performance strengthened significantly in June despite continued weakness in selected manufacturing industries. Export growth was led by the technology sector, as computer exports surged 290.7% YoY on the back of robust global demand for AI servers and high-performance computing (HPC) infrastructure. As a result, South Korea recorded a record trade surplus of USD 26.95 billion, up from USD 23.75 billion in the previous month. The country’s leadership in the global AI supply chain provides underpinning for positive economic outlook.
Taiwan’s TWSE Index gained 3.11% during the month, easing from a 14.92% rise in May. The market remained resilient despite weaker sentiment across the global technology sector. Although investors rotated out of high-flying AI and semiconductor stocks amid profit-taking, the broader market remained supported by Taiwan’s strong macroeconomic fundamentals. Export orders continued to exceed expectations, driven by robust global demand for AI servers, high-performance computing (HPC), and cloud infrastructure. The continued strength in Taiwan’s technology supply chain, coupled with improving earnings visibility for leading semiconductor companies, helped offset weakness in selected technology names. Taiwan’s central bank kept its benchmark discount rate unchanged at 2.0% in June, in line with market expectations, maintaining its highest policy rate since 2008. While the decision reflected a cautious approach, two board members voted in favour of a rate hike, signalling a mildly hawkish bias. The central bank reiterated that it remains vigilant on inflation, particularly in the second half of 2026, while maintaining 2% inflation as a medium- to long-term target. Policymakers are expected to remain data dependent as they monitor inflation trends, energy prices, and ongoing geopolitical uncertainties.
Singapore’s STI advanced 2.64% in June, supported by continued strength in the manufacturing sector. Singapore’s manufacturing activity remained resilient, with the Electronics PMI rising to 52.2, its highest level since May 2018, while the Overall PMI increased by 0.3 points to 51.3, marking its strongest reading since November 2018. The expansion was broad-based, reflecting sustained AI-driven demand. Key sub-indices all improved during the month: new orders rose to 52.8 from 52.5 in May, new export orders increased to 52.3 from 51.9, output strengthened to 52.1 from 51.7, employment edged up to 51.7 from 51.4, and future business expectations improved to 52.3 from 52.0. The broad-based improvement reinforces the positive outlook for Singapore’s manufacturing and technology sectors. These trends are expected to underpin Singapore’s projected GDP growth of 4.0% in 2026, with the current manufacturing expansion likely to be sustained through at least 3Q26.
Malaysia’s KLCI declined 1.13%% in June, reflecting weaker investor sentiment amid signs of moderating economic growth. Malaysia’s Producer Price Index (PPI) accelerated to 7.8% YoY in May, marking its fastest pace since June 2022. The increase was driven primarily by the mining sector, where producer prices surged 52.6% YoY following a sharp rise in crude oil extraction prices. Manufacturing PPI also strengthened to 3.5% YoY, led by higher prices for refined petroleum products and electronic and optical products, while agriculture, forestry and fishing recorded an 8.9% YoY increase, the strongest reading in 14 months. Upstream cost pressures remained elevated, with crude materials for further processing rising 31.5% YoY, the fastest pace since December 2021. As PPI inflation exceeded CPI inflation for a second consecutive month, upside risks to consumer inflation have increased, with firms likely to pass on higher input costs if elevated producer prices persist amid ongoing supply disruptions. The Ringgit declined against USD significantly during the month, largely due to the strength of the USD as well as uncertainties in Malaysia’s political situation.
Thailand’s SET Index edged down 1.46% in June. Thailand’s economy delivered a stronger than expected performance in 1Q26, with real GDP expanding 2.8% YoY and 0.7% QoQ on a seasonally adjusted basis. Growth was supported by increased investment, stronger goods exports, higher government spending, and resilient private consumption. However, the improvement does not yet signal a fundamental shift in the economy’s growth trajectory. Beneath the headline figures, Thailand’s economic momentum remained uneven. Exports rose 10.6% YoY to USD 34.3 billion in May, but growth slowed significantly from April and came in below market expectations, marking the weakest expansion since February due to softer shipments to China. Industrial exports remained resilient, supported by strong demand for computers and telecommunications products, while automotive and agricultural exports weakened. Meanwhile, imports surged 35.1% YoY to USD 40.0 billion, driven by stronger domestic demand, policy stimulus, and higher imports of fuel, raw materials, and capital goods. On a year-to-date basis, exports and imports increased 17.0% and 35.6%, respectively, reflecting resilient trade activity despite a moderation in export growth.
Jakarta Composite Index continued to weaken declining 7.90% on concerns over potential downgrade by MSCI agency to frontier market status, worries about fiscal and external balances because of rising oil prices, and fear of greater State intervention in the commodities sector. Year to June, the market had declined by 39.13%. Indonesia recorded a trade deficit of USD 1.61 billion in May, reversing April’s USD 0.09 billion surplus and ending a six-year streak of monthly trade surpluses. The deterioration was driven by a sharp increase in imports (+22.16% YoY) alongside a decline in exports (-5.7% YoY). The oil and gas trade deficit widened significantly to USD 3.76 billion from USD 1.53 billion in May 2025, while the non-oil and gas surplus narrowed to USD 2.15 billion from USD 5.83 billion. The weaker trade balance reflected the combined impact of rupiah depreciation and elevated global oil prices, which increased import and transportation costs. Rising geopolitical tensions in the Middle East also contributed to higher energy prices, highlighting Indonesia’s vulnerability to external shocks and posing near-term risks to the country’s external balance. Bank Indonesia, the Indonesia Central Bank, raised the benchmark interest rates by 25bps twice to 5.75%, aiming to stabilize the Rupiah and to keep inflation in check.
The Philippines PSE Index gained 4.65% in June, a break from the losses that the market had sustained in the previous 3 months. The gain was supported by bargain hunting following two weeks of sustained weakness, which triggered a technical rebound. Investor sentiment also improved after May inflation came in below expectations at 6.8% YoY (consensus:7.8%), although ongoing geopolitical tensions in the Middle East and domestic political uncertainty continued to cap market upside. The rally was led by ICT (+13.6%), Jollibee Foods (+7.4%) and Aboitiz Equity Ventures (+5.7%). Meanwhile, the country’s external sector remained resilient, with exports rising 6.3% YoY to USD 7.21 billion in April, marking the 16th consecutive month of expansion. Total exports reached USD29.93 billion during the first four months of 2026, the strongest January–April performance in more than four years, supported by the electronics sector, which accounted for nearly 48% of total exports. On the banking front, the gross non-performing loan (NPL) ratio edged up to 3.37% in April from 3.29% in March, but slightly eased from 3.39% a year earlier, as borrowers faced tighter economic conditions amid the Middle East war. Soured loans reached PHP 579.885 billion during the month, climbing by 11.68% YoY from PHP 519.234 billion. Meanwhile, BSP data showed that the industry’s total loan portfolio rose 12.1% YoY to PHP 17.2 trillion in April, despite a modest 0.4% MoM decline.
Vietnam’s VN-Index edged down 0.19% in June despite continued strength in economic fundamentals. Industrial production remained robust, with output rising 12.7% YoY in June, driven by a 12.6% increase in manufacturing and an 8.7% gain in electricity production, reflecting sustained global AI-driven demand and resilient supply chain diversification despite geopolitical uncertainty and elevated energy costs. Foreign direct investment (FDI) continued to support growth, with realized FDI increasing 11.2% YoY to USD 13.0 billion in the first half of 2026, while registered FDI surged 61% to USD 34.7 billion, pointing to a strong investment pipeline and the potential for record inflows this year. However, the external sector weakened as the trade balance swung to a deficit of approximately USD 15 billion in 1H26 from a USD 7.9 billion surplus a year earlier, largely due to higher energy import costs following the escalation of Middle East tensions. Nonetheless, easing geopolitical tensions and moderating energy prices are expected to support a gradual improvement in the external balance, with the trade account likely to return to surplus by the end of 2026.
The shift to a dovish monetary stance in the US at the start of 2026 appears now to have been upended by the war in the Middle East. After an almost 12 months of twist and turns in the US tariff saga, the market is still divided on impact of higher tariffs on macro variables such as inflation and economic activities. Meanwhile, US corporate earnings, especially in the technology sector, continue to be key pillar to hold up risk assets. US market valuations are at historical high, and the high valuation is further driven by strong capital expenditure drive for AI, which has raised questions as to whether the humongous expenditures in AI will generate the anticipated returns. The semiconductor and AI investment cycle may move into a more difficult phase as investors will start to be more discerning with regard to their return on investment. If and when the supply and demand dynamic in the semiconductor cycle should turn, on the margin, with supply capacity expanding at a time when global demand soften on lower GDP growth outlook, headwinds for the industry can be expected.
Geo-political developments as well as policy directions in the major economies, in particular US and in China, remain on our radar screen. The market is still watchful of developments in Trump’s tariffs for the key trade partners. The US tariffs scene has been marked by changes, and uncertainties remain. Meanwhile, new geo-political fissures have opened up with the recent US military raid and capture of Venezuela President, Nicolas Maduro Moros, and the repeated utterings by President Trump of his intention to bring Greenland within the US fold, militarily if necessary. Adding to these is the flare up of the military conflict between the US/Israel and Iran that has engulfed the entire Middle East and choked the supply of crude oil and LNG from the region to the world. These developments further heightened tension in global geo-politics. In the near term, the US mid- term election to be held in the later part of 2026 may change the balance of power in the US Congress and have significant impact on US policies in the remaining years of Trump’s term. These developments will create uncertainties for investors. The duration of the Middle East war has added to uncertainty in global growth outlook as supply chain disruptions in energy sources among other things push inflation higher and change macro variables assumption.
In Asia, the focus is on the pace of China’s economic recovery which has been weaker than expected. The tariff issues with the US and continuing efforts to broaden restrictions on sales of tech equipment and services to Chinese entities can only exacerbate the economic situation in China. The Chinese property sector continues to face challenges, and any sign of stabilization and growth will have positive catalyst for China’s economy and risk assets. The Chinese government continues to bring forth measures to help the economy. The Chinese government remains constructive on policies to spur economic activities to achieve economic growth target. The various measures have boosted market sentiments. However, the longer- term effectiveness on China’s economy continues to be closely watched. It may take time for the initiatives to bear fruits. The focus will be on addressing the challenges in the property market, lifting consumer sentiments and consumption, and countering the effects of the new US tariffs.
On external trade, countries with high export dependency for growth in the Asia region including ASEAN will face significant challenges arising from the US tariff policies. The disruption in supply chain realignment may result in temporary mismatch in corporate earnings delivery against market expectation during the initial stage of tariff implementation. To-date, while ASEAN countries’ exports to the US have been impacted by the tariffs, these countries have been able to mitigate the impact on the economic growth through trade diversifications. Many of these countries have now to also contend with having to manage disruptions in energy supplies and the ensuing price escalations.
While interest rates have started to be eased, there remains headwind for risk assets, including the impact of the still high interest rate on business and economic activities, uncertainties in US policies, the historically high market valuations in the US, the geo-political tension in various parts of the world and resulting disruptions to energy supplies, as well as the still slower than expected economic growth in China. However, in the investment space we are in, we believe there is room for cautious optimism. After years of prolonged sell down, and despite the upticks in recent months, China equities remain under-owned and their favourable valuation offer potential upside, particularly following the recent rounds of significant policy change initiatives from China.
We continue to apply our strategy of focusing on identifying fundamentally healthy companies with low valuations, low leverage, high growth, robust management and a strong track record, and adherence to our investment philosophy of “Never Fully Invest at All Times” which has served us well over the years.
We thank you once again for your continued faith in us and hope to remain good stewards in our endeavour to protect and grow your capital.